How Canadians Struggling with Cross-Border Debt Can Learn from U.S. Debt Relief Programs: A 2026 Guide
How Canadians Struggling with Cross-Border Debt Can Learn from U.S. Debt Relief Programs: A 2026 Guide
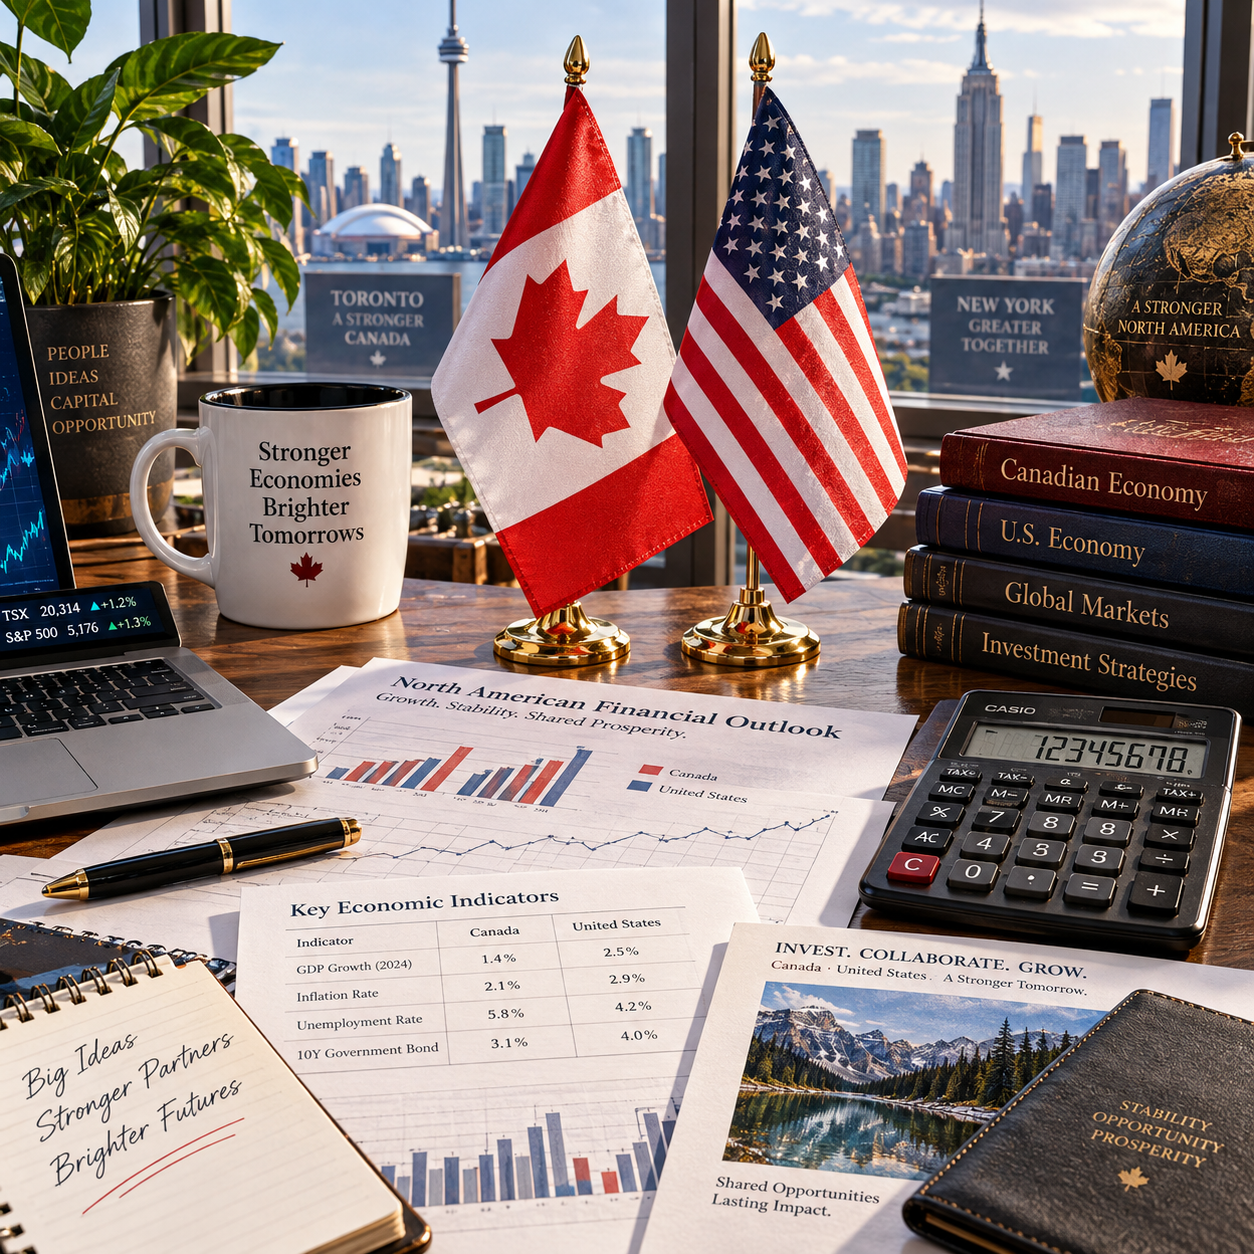
I've spent a lot of time lately talking to friends, clients, and readers who moved to the U.S. for work, retired part-time in Arizona or Florida, or simply racked up debt in American dollars during a cross-border business venture. And a pattern keeps showing up: Canadians with USD-denominated debt often feel stuck between two systems that don't talk to each other. Our credit bureaus don't automatically sync with American ones, our legal protections don't extend past the border, and most Canadian debt relief professionals have never had to deal with a U.S. collection agency calling about a hospital bill from Texas.
That's actually why I think it's worth Canadians paying closer attention to how the U.S. debt relief industry operates in 2026. Not because we should abandon our own regulated system — Canada's licensed insolvency framework is genuinely strong — but because the U.S. market is more competitive, more transparent in certain states, and offers a useful mirror for what consumer protection and pricing clarity should look like here at home.
Cross-Border Debt 101: What Makes It Different
Debt that spans two countries isn't just 'regular debt with an accent.' It comes with layers most people don't think about until they're neck-deep in it. Currency exchange rates can quietly inflate what you owe if the loonie dips against the dollar. Credit reporting is siloed — Equifax Canada and TransUnion Canada don't automatically communicate with their U.S. counterparts, so a settled U.S. debt might not even register on your Canadian credit file, for better or worse. And legal jurisdiction gets messy fast: a collection agency operating under Texas law follows very different rules than one bound by Canadian provincial collection statutes.
Common Sources of Cross-Border Debt
The scenarios I hear most often include:
- Snowbirds who racked up unexpected U.S. medical bills after an emergency room visit during a Florida winter
- Remote workers paid in USD who financed cars, apartments, or credit cards while living stateside
- Dual citizens who left the U.S. with student loans or credit card balances still open
- Canadians who relocated for a job, then moved back home leaving behind unresolved debt obligations
Why Canadian Debt Relief Options Feel Limited by Comparison
Here's the honest truth: Canada's system is narrower. We have consumer proposals, credit counseling, and bankruptcy — all administered through Licensed Insolvency Trustees (LITs). It's a tightly regulated, trustworthy path, but it doesn't offer the variety Americans have. There's no Canadian equivalent to the sprawling U.S. debt settlement industry, and that gap is exactly where a lot of Canadians get confused about their options when the debt itself originated south of the border.
How the U.S. Debt Relief Industry Works — And What Canada Can Learn
In the U.S., consumers can choose between debt settlement companies (negotiating lump-sum reductions with creditors), debt management plans (structured repayment through nonprofit credit counselors), debt consolidation loans, and traditional credit counseling. It's a much larger, more commercialized space — which comes with both opportunity and risk.
What impresses me is how certain states have stepped up to police this industry through independent oversight and journalism. Texas is a great case study. State regulators require registration for debt settlement providers, and consumer-facing reporting has emerged to fill the transparency gap.
State-Level Oversight as a Model
This is where the Texas Tribune: Best Debt Relief Programs in Texas 2026 comes in as a genuinely useful resource. The Tribune's reporting walks through vetted companies by comparing fee structures, complaint histories, and actual success rates — the kind of side-by-side comparison Canadian consumers almost never get at a provincial level. We simply don't have an equivalent independent outlet doing this kind of ongoing, localized accountability journalism for debt relief services in Ontario or British Columbia.
The takeaway for Canadians isn't 'go hire a Texas company.' It's this: before committing to any debt relief provider — American or Canadian — you should be comparing accreditation, checking complaint histories with regulators, and demanding a clear breakdown of fees in writing. That standard of scrutiny, which Texas media has helped normalize, is something we should be asking for regardless of which side of the border the company operates on.
Comparing Costs — U.S. Debt Settlement vs. Canadian Consumer Proposals
Let's talk numbers, because this is where things diverge sharply.
- U.S. debt settlement: Typically charges 15–25% of the enrolled debt amount, paid once settlements are finalized. Timelines run 24–48 months. Credit score impact is often severe short-term, since accounts usually go delinquent before settlement.
- Canadian consumer proposals: Administered by an LIT with regulated, disclosed fees built into the proposal itself — no surprise percentage cuts. Timelines run up to 5 years, and while credit is impacted, the process is more predictable and transparent from day one.
For Canadians settling USD debt while earning or holding CAD, currency risk adds another layer of unpredictability — a settlement negotiated in U.S. dollars can become more or less expensive purely based on exchange rate swings between the agreement date and the payment date.
Tax and Legal Implications for Canadians Using U.S. Programs
One thing people frequently overlook: forgiven debt can trigger tax consequences. In the U.S., settled debt is often reported as taxable income via a 1099-C. Canadians need to understand how the CRA treats cross-border forgiven debt, because it's not always straightforward, and a mistake here can create a second financial headache. This is genuinely a situation where getting cross-border legal and tax advice before enrolling in any U.S. program isn't optional — it's essential.
Consumer Protections — Where Canada Is Ahead (and Where It Lags)
Canada's Licensed Insolvency Trustee system is, frankly, one of the more consumer-protective frameworks in North America. LITs are federally regulated, bound by strict conduct rules, and accountable to the Office of the Superintendent of Bankruptcy. The FCAC and provincial regulators add further oversight layers.
The U.S. picture is more fragmented. The CFPB and state attorneys general provide oversight, but enforcement varies wildly by state, and the debt settlement industry has a documented history of predatory actors. That said, resources like the Texas Tribune's vetted list show that strong, localized accountability journalism can partially fill regulatory gaps — something Canada could genuinely benefit from replicating provincially.
Practical Steps for Canadians Dealing with Cross-Border Debt
If you're navigating this right now, here's the checklist I'd walk through:
- Verify any company's licensing status in both the U.S. state and, if applicable, in Canada
- Consult a Licensed Insolvency Trustee before enrolling in any American debt relief program
- Calculate your FX exposure if the debt or settlement is USD-denominated
- Use independent journalism and state-specific consumer guides as due-diligence tools, even if you never plan to work with a company based there
- Get written fee disclosures and confirm there are no upfront charges before services are rendered
FAQ — Cross-Border Debt Relief for Canadians
Can a Canadian use a U.S. debt settlement company? Technically yes, though most reputable firms require you to have U.S.-based debt and sometimes a U.S. address or bank account, so eligibility varies case by case.
Will U.S. debt relief affect my Canadian credit score? Not directly, since the bureaus don't sync — but if the U.S. debt is with a creditor that reports internationally or sells to a Canadian collection agency, it absolutely can.
Is debt forgiveness taxable in Canada? It can be, depending on the type of debt and how it's structured. Speak with a cross-border tax professional before assuming otherwise.
Conclusion
Canada and the U.S. run genuinely different debt relief systems, and I wouldn't recommend abandoning Canada's regulated LIT process for an unfamiliar American alternative without serious due diligence. But there's real value in studying how transparent, well-regulated resources — like the Texas model highlighted by the Tribune — set a benchmark for cost clarity and consumer accountability. Canadians dealing with cross-border debt should borrow that mindset: demand transparency, verify credentials, and always loop in a licensed Canadian professional before making any final decision that crosses the border.